


How Long Do You Have to File a Hail or Storm Damage Roof Claim in Texas or Oklahoma?
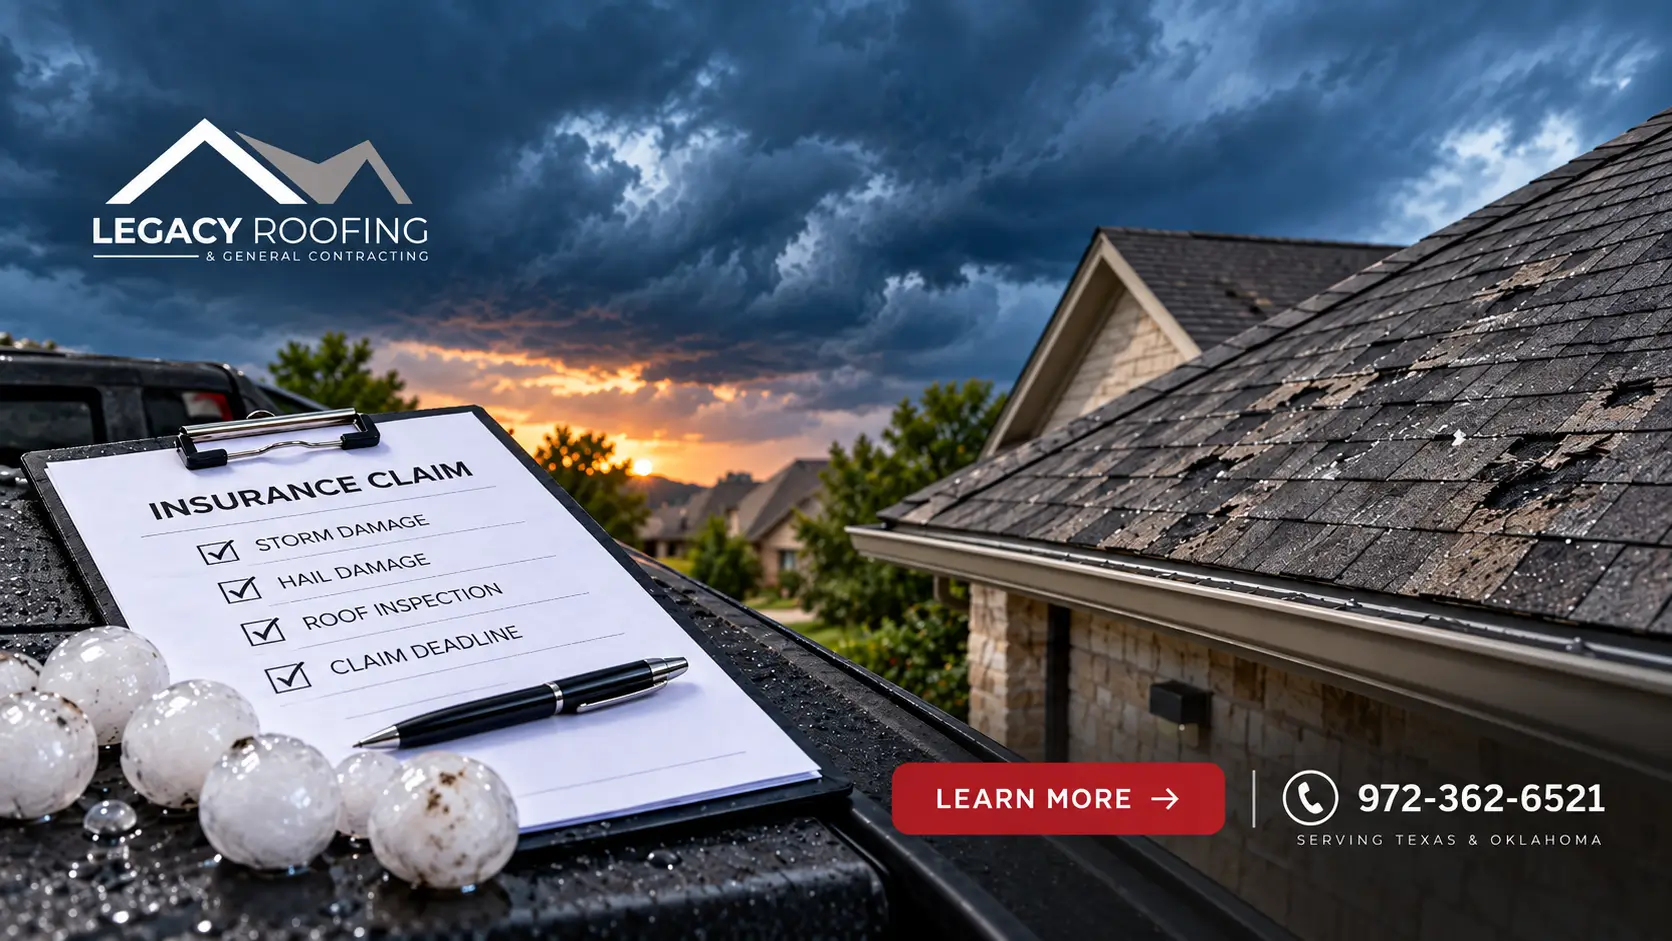
A hailstorm can pass through your neighborhood in minutes, but roof damage may not become obvious until weeks or months later.
That creates an important question for homeowners: how long to file a hail damage claim in Texas, and what happens if the property is in Oklahoma?
There is no single deadline that applies to every homeowners insurance policy in both states.
Texas regulators tell homeowners to notify their insurer as soon as possible because insurance policies commonly contain filing deadlines. Some policies use a one-year deadline. Special rules also apply to Texas Windstorm Insurance Association policies and certain coastal wind and hail coverage.
Oklahoma has a specific protection for certain roof claims involving damage that was not evident without an inspection. When a policy specifies a time limit for wind or hail roof damage, Oklahoma law requires it to permit qualifying claims after the first anniversary of the loss, but no later than 24 months after the loss.
The safest approach in either state is simple: inspect the roof after a significant storm, review your policy, document damage, and notify your insurer promptly if you believe you have a covered loss.
Legacy Roofing & General Contracting helps homeowners throughout Texas and Oklahoma evaluate roofing conditions after hail, wind, and severe storms.
How Long to File a Hail Damage Claim in Texas?
Texas does not have one universal hail claim deadline that overrides every homeowners policy.
Your policy matters.
The Texas Department of Insurance advises homeowners to tell their insurance company about damage as soon as possible. TDI notes that most insurance companies have filing deadlines and that some policies provide a one-year deadline unless the policyholder can show good cause for filing later.
That means homeowners should not assume they automatically have two years, three years, or any other general period to report hail damage.
Check Your Policy Before Assuming the Deadline
Look for sections titled:
- Duties after loss
- Notice of loss
- Property conditions
- Wind and hail endorsement
- Claim filing period
- Proof of loss
- Suit against us
The wording may establish responsibilities that begin immediately after the storm.
If you do not understand the policy language, contact your insurance company or licensed insurance agent for clarification.
Special Texas Coastal Rules
For certain wind and hail policies in Texas catastrophe areas, state law allows policy provisions requiring a claim to be filed within one year of the loss, provided the policy also allows later filing for good cause under the applicable rules.
Texas Windstorm Insurance Association policies also generally require claims within one year of the date of damage, although an extension of up to 180 days may be available for good cause.
Homeowners in inland markets such as Dallas-Fort Worth should still check their individual policy rather than applying coastal rules to their situation.
What Is the Roof Insurance Claim Deadline in Oklahoma?
The roof insurance claim deadline in Oklahoma has an important rule specifically addressing wind and hail damage that may not be immediately visible.
Oklahoma Insurance Department guidance explains that when a policy specifies a time limit covering roof damage caused by wind or hail, the policy must allow certain claims to be filed after the first anniversary of the loss, but no later than 24 months after the date of loss, when the damage was not evident without inspection.
This does not mean every Oklahoma homeowner should wait two years.
The Oklahoma Insurance Department still advises consumers to contact their insurance company as soon as possible after a disaster.
Why Hidden Hail Damage Matters
Some hail damage is easy to see.
Other damage may require closer evaluation, such as:
- Shingle bruising
- Impact fractures
- Concentrated granule loss
- Damage around roof penetrations
- Dented flashing
- Damaged vents
- Problems on slopes that cannot be seen from the ground
This is one reason the Oklahoma Insurance Department encourages roof inspections after major wind or hail events.
Property owners can explore roofing assistance in Oklahoma City if they are concerned about recent storm damage.
What Is a Storm Damage Claim Filing Window?
A storm damage claim filing window is the period during which the policyholder is expected or permitted to report a loss under the applicable insurance policy and law.
The important part is that several different deadlines may exist.
Claim Notice Deadline
This involves notifying your insurance company that damage occurred.
Proof of Loss Deadline
Some policies may require additional documentation or a signed proof of loss within a particular period.
Repair or Replacement Deadline
Replacement cost policies sometimes establish timelines for completing repairs and requesting recoverable depreciation.
Lawsuit Deadline
A legal deadline for bringing a lawsuit against an insurer is separate from the deadline for reporting the original property claim.
Confusing these deadlines can create serious problems.
Statute of Limitations in Texas for Roof Insurance Claims
Homeowners sometimes search for the statute of limitations in Texas for roof insurance claims and assume it tells them how long they can wait before notifying their insurer.
It does not work that way.
Texas law generally restricts contractual provisions that attempt to shorten the period for bringing certain contract suits to less than two years. TDI's residential-property guidance specifically references this minimum contractual limitation framework.
Certain wind and hail insurance policies in Texas catastrophe areas are subject to more specific rules. Texas Insurance Code Section 2301.010 permits qualifying policy forms to use a contractual lawsuit deadline that may not end earlier than the earlier of two years after the insurer accepts or rejects the claim, or three years after the loss.
These lawsuit provisions should not be interpreted as permission to wait that long to report roof damage.
If a dispute is approaching a legal deadline, homeowners should speak with a qualified Texas attorney about their specific circumstances rather than relying on a general roofing article.
What Should You Do After a Hailstorm?
Fast action can make documentation easier.
You do not need to climb onto your roof.
Step 1: Record the Storm Date
Write down the approximate date and time of the storm while it is fresh in your memory.
Save severe-weather alerts, photographs, or other information you already have.
Step 2: Check the Property Safely
From ground level, look for:
- Shingles on the lawn
- Dented gutters
- Damaged downspouts
- Broken screens
- Damaged siding
- Fallen branches
- Dents on exposed metal
- Water stains inside the house
These signs do not automatically prove covered roof damage, but they may justify a closer inspection.
Legacy Roofing's guide to identifying hail damage on a roof explains additional signs homeowners may notice after severe weather.
Step 3: Document Visible Damage
Take clear photographs and videos.
Do not discard damaged materials before your insurer has had an appropriate opportunity to evaluate them when your policy requires inspection.
Both Texas and Oklahoma regulators advise consumers to document storm losses and make reasonable temporary repairs to prevent additional damage.
Step 4: Review Your Deductible
Check your declarations page.
Texas and Oklahoma policies may have separate wind or hail deductibles.
Knowing your deductible can help you understand the financial side of a potential roof hail damage insurance claim.
Step 5: Arrange a Roof Inspection
Hail damage can be difficult to evaluate from the ground.
A professional roofer can assess the roofing system and document visible conditions.
Homeowners preparing for an insurance conversation can use this roof inspection checklist for insurance claims.
Step 6: Contact Your Insurance Company
If there appears to be storm damage that may be covered, contact your carrier according to your policy requirements.
Do not delay simply because there is no active interior leak.
Filing a Claim for Storm Damage Repairs
Filing a claim for storm damage repairs generally begins with notifying the insurance carrier.
Be prepared to provide information such as:
- Policy number
- Date of loss
- Type of storm
- Areas of visible damage
- Photographs
- Contact details
- Temporary repair receipts
Your insurance company may then assign an adjuster to inspect the property.
Legacy Roofing & General Contracting can inspect the roof, document roofing conditions, and prepare estimates for roofing work. Insurance coverage decisions, policy interpretation, and claim settlement decisions remain matters for the homeowner and insurance carrier.
For a broader explanation of the process, review Legacy Roofing's roof insurance claim help guide.
What Does a Hail Damage Roof Insurance Claim Cover?
A hail damage roof insurance claim may involve covered physical damage caused by a hail event, but coverage depends entirely on the policy.
Potential roofing components affected by hail can include:
- Asphalt shingles
- Metal roofing
- Flashing
- Ridge caps
- Gutters
- Roof vents
- Skylights
Policies can include separate deductibles, exclusions, cosmetic-damage provisions, actual-cash-value schedules, or replacement-cost terms.
Do not assume that every hail mark qualifies for replacement or that every roof claim receives the same settlement.
You can read more about common roofing and insurance issues in Legacy Roofing's hail damage roof insurance claim resource.
Does a Hail Damage Claim Raise Home Insurance Rates?
The answer depends partly on where you live.
Texas
Does hail damage claim raise home insurance rates in Texas?
Texas provides an important consumer protection.
The Texas Department of Insurance states that home insurance companies cannot charge you more because of claims for damage from natural causes, including weather. TDI also says companies cannot charge more for a claim they did not pay.
That does not mean your overall premium can never increase after a storm season.
Rates can change because of broader factors such as regional losses, rebuilding costs, insurer rate changes, property characteristics, and market conditions.
Oklahoma
Oklahoma handles claims history differently.
The Oklahoma Insurance Department lists claim history as one of the factors insurers may consider when calculating homeowners premiums.
OID also states that a company generally may not cancel, non-renew, or increase the premium of a homeowners policy that has been in effect for more than 45 days solely because the insured filed a first claim. Additional claims can create different considerations.
For policy-specific answers, contact your insurer or licensed agent.
Why Waiting Can Make a Roof Claim More Complicated
Even when a policy allows significant time to report a claim, waiting can make it harder to determine what caused the damage.
During the delay, the roof might experience:
- Additional hail
- High winds
- Heavy rainfall
- Normal aging
- Heat exposure
- New leaks
- Previous damage becoming worse
The longer several events overlap, the harder it may become to associate a specific condition with a particular storm.
Early inspection and documentation can create a clearer record.
Roof Inspection Help Across Texas and Oklahoma
Legacy Roofing & General Contracting provides residential roofing inspections, repairs, and replacements in communities throughout Texas and Oklahoma.
Homeowners affected by severe weather can find local roofing assistance in markets including Austin, Tulsa, Dallas-Fort Worth, San Antonio, Houston, and Oklahoma City.
You can also review Legacy Roofing & General Contracting's Google Business Profile and customer feedback when researching a roofing contractor.
Frequently Asked Questions About Hail and Storm Claim Deadlines
How long to file a hail damage claim in Texas?
There is no universal deadline for every Texas homeowners policy. TDI recommends notifying your company as soon as possible and notes that some policies have a one-year filing deadline. Review your policy for the exact requirement.
Is there a two-year deadline for Texas hail claims?
Do not assume so. Legal deadlines for filing a lawsuit are different from insurance-policy requirements for reporting a claim. Your policy may require much earlier notice.
What is the Oklahoma roof insurance claim deadline?
Policy terms matter, but Oklahoma has a special rule for certain hidden wind or hail roof damage. If a policy specifies a time limit, it must allow qualifying claims involving damage not evident without inspection after one year and up to 24 months after the date of loss.
Should I wait to see if my roof starts leaking?
No. A roof can have hail damage without immediately leaking. If significant hail affected your property, consider having the roof inspected while the storm date and surrounding property damage can still be documented.
Does filing a hail claim increase insurance rates in Texas?
Texas says home insurers cannot charge a homeowner more because of a claim for damage from natural causes, including weather. However, overall premiums may change for broader pricing or regional risk reasons.
Can an Oklahoma insurer raise my rate after a hail claim?
Oklahoma insurers may consider claims history when setting rates, but state guidance says a company may not increase a homeowners premium solely because of a first claim on a qualifying policy that has been in effect more than 45 days. Individual circumstances vary.
What if I discover hail damage months after the storm?
Document what you find and review the policy immediately. Contact the insurer promptly. Oklahoma provides specific protection for certain wind or hail roof damage that was not evident without an inspection, while Texas deadlines depend more heavily on the specific policy and type of coverage.
Should I call a roofer or insurance company first?
If there is emergency damage, protect the property from additional loss and contact the insurer promptly. A professional roofing inspection can also help you understand the physical condition of the roof. For more guidance, review whether to call a roofer or insurance company first.
Do Not Let an Unknown Deadline Decide for You
The most important lesson about a storm damage claim filing window is not to assume you have plenty of time.
Texas and Oklahoma have different rules, individual insurers have different policies, and a claim-notice deadline is not the same as a legal deadline for filing suit.
After significant hail or wind, document visible damage, read your policy, arrange an inspection when appropriate, and contact your insurance company promptly.
Legacy Roofing & General Contracting can help evaluate the condition of your roofing system and explain repair or replacement options after a storm.
Contact Legacy Roofing & General Contracting to schedule a professional roof inspection in Texas or Oklahoma.


